Gerry Morton

Writing

Where I’ve landed.

Positions I have arrived at across building companies, chairing a board through a turnaround, six years on a public commission, twenty-two years of writing about energy, and sitting in confidential rooms with people working through the same decisions.
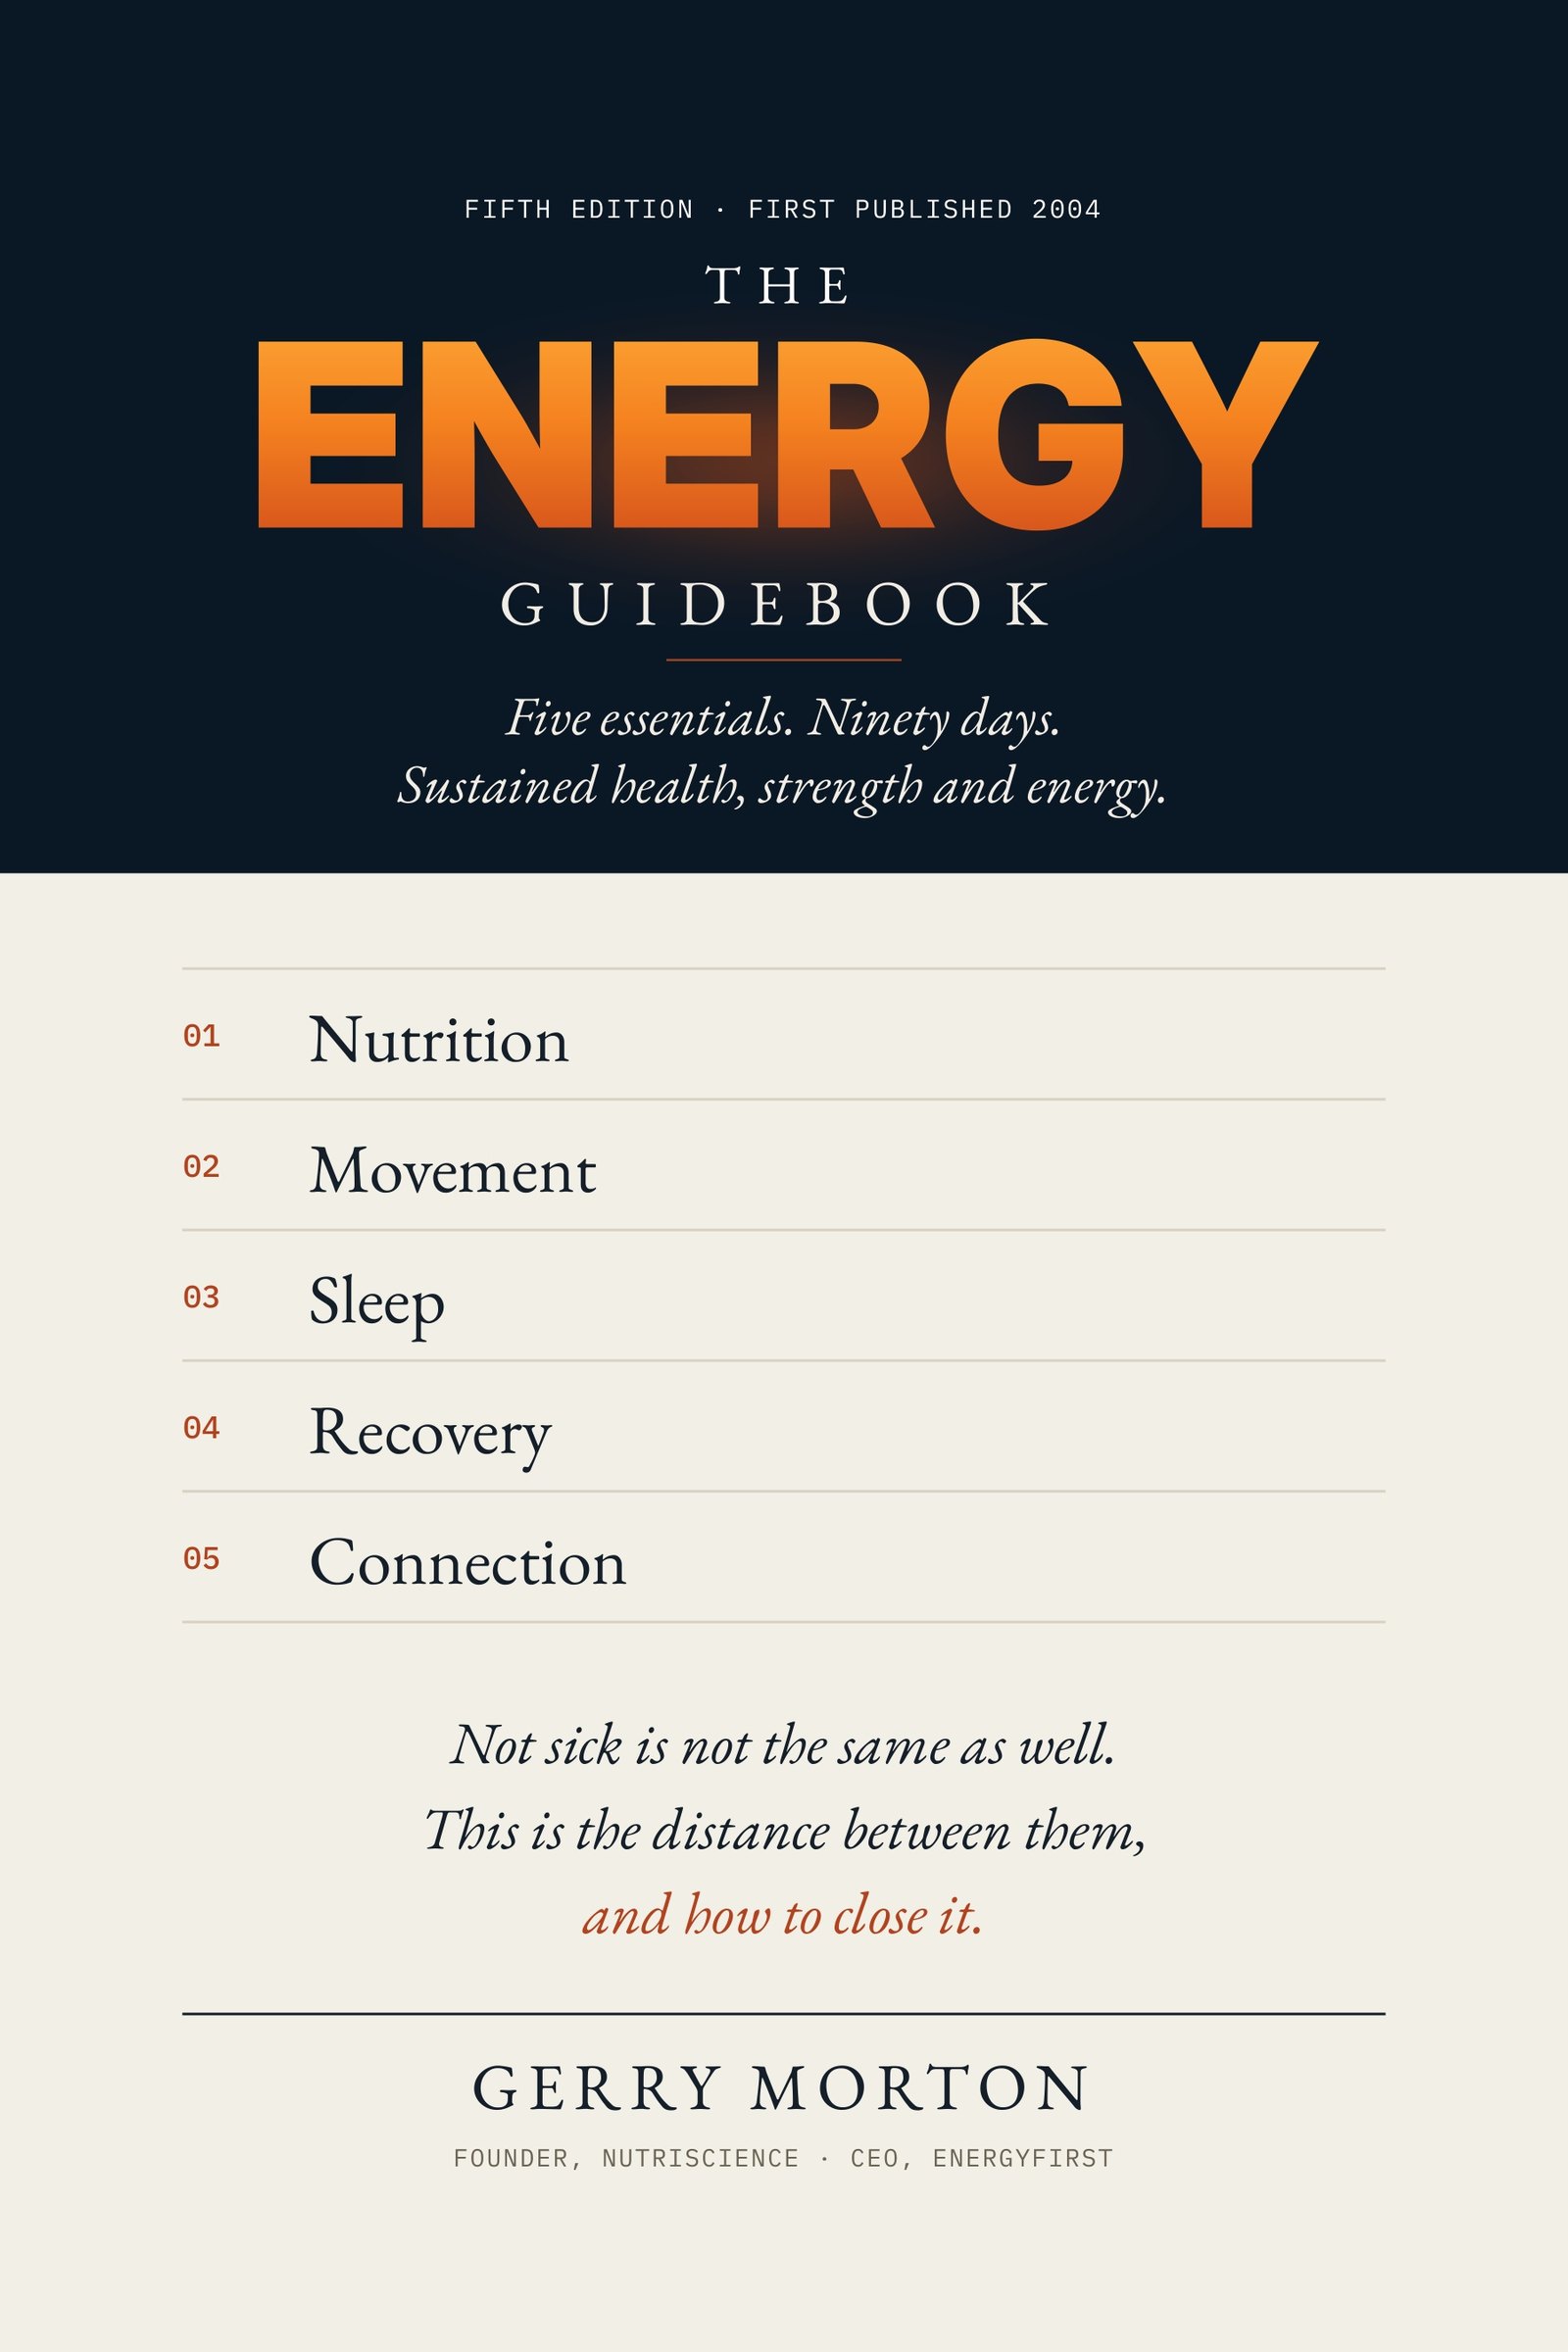
The Energy Guidebook, fifth edition, by Gerry T. Morton
The book

The Energy Guidebook, Fifth Edition

Five essentials for sustained health, strength and energy: nutrition, movement, sleep, recovery and connection. Then ninety days to put them in place, one change at a time, with more than 500 citations behind it.

About the book
Leading the Room by Gerry Morton, working cover
The book in progress

Leading the Room

How to lead any room where people gather: board meetings, family dinners, peer groups and book clubs. Drawn from twenty-two years of leading rooms across Vistage, EO, YPO and TIGER 21. Each month I send one practice from it to anyone who leads a room.

Join The Room Letter

Governance

What a board owes an institution

When I became Chairman of the Board and Council President for Boy Scouts of America in Los Angeles, the organization had been losing millions of dollars a year for several years running. What struck me was not the deficit. It was that the deficit had a history. Every year of it had happened under a board, and every one of those boards had been full of accomplished, well-intentioned people who showed up.

That is the part worth sitting with. A board can be fully engaged and still preside over decline, because attendance is not the same as ownership.

I have come to think a board owes an institution three things, and only one of them is oversight.

The first is a timeline longer than any director’s tenure. Our council carried $13.2 million in debt when I took the chair. We retired all of it and produced a $1 million operating surplus within two years. That got attention, and it was the least durable thing we did. The work that mattered more was raising over $25 million in development dollars, including a $10 million gift that permanently endowed Lake Arrowhead Scout Camp. An endowment is a decision made by people who will not be in the room when it pays off. That is the test.

The second is a willingness to change the shape of the thing. We led the merger of the Los Angeles Area and San Gabriel Valley Councils into the Greater Los Angeles Area Council, now one of the largest in the country. Mergers are usually described in financial terms. In practice a merger is a governance act: two boards, two cultures, two sets of loyalties, and a set of decisions about who leads what afterward. The financial case took a few months. The governance work took the rest of my term.

The third is patience, which is the one nobody puts in a board deck. Turning that organization around took slower and more careful work than any business deal I have done. There was no single decision that fixed it. There was a sequence of unglamorous ones, held steady long enough to compound. The Journey to Excellence Gold Award we earned in 2017, up from no ranking at all in 2014, was the output of three years of that, not of a strategy offsite.

When I look at a board now, I ask a narrow question: what has this board decided that will only pay off after everyone currently sitting on it has left? If there is no good answer, the board is supervising, not governing.

Peer groups

Why a room of peers beats a room of advisors

I have spent twenty-two years inside rooms of this kind: Vistage and Entrepreneurs’ Organization starting in 2004, YPO since 2017, and TIGER 21 since 2024, where I now chair two Groups. The question I get most from people considering one is reasonable: I already pay for good advice, so what does a room of peers add?

Here is the honest answer. Advisors are paid, and being paid shapes what gets said. That is not a character problem. A banker with a mandate, a lawyer with a retainer, and a wealth manager with assets under management are all giving you their best judgment through the filter of a relationship they would like to keep. The filter is usually invisible and almost always polite.

A peer in a confidential room has nothing to sell you. That single fact changes the quality of what you hear.

Three things follow from it.

The first is that peers question the problem before they answer it. An advisor is engaged to solve the problem you brought. A room of people who have run companies will spend the first hour establishing whether you brought the right problem. Most of the value I have watched get created in these rooms happened in that first hour.

The second is that the useful part of the room is the failures. Everyone can find someone to tell them how a deal is structured. It is much harder to find someone who will say, without flinching, that they did the same thing and it cost them. People will only say that in a room where it cannot travel. Confidentiality is not a courtesy in a peer Group. It is the mechanism.

The third is that the room only works if nobody performs. A group of accomplished people has a natural gravity toward the highlight reel, and once one person starts, the hour is gone. Most of the actual craft of chairing is protecting against that. It is also why I care more about what a Group says about itself than what a Chair says about it.

None of this makes advisors less valuable. I use them. It makes them a different instrument. Advisors work on the problem in front of you. A good room works on your judgment, and your judgment is what you will be using long after the current problem is closed.

I am writing a book on how to lead any room where people gather: Leading the Room. Each month I send one practice from it to anyone who leads a room. Join The Room Letter.

Wealth transitions

The question that comes after the wire clears

Most of the planning around a liquidity event happens before it. The structure, the tax work, the timing, the negotiation. All of it is pointed at the closing date, and it is usually done well, because the people doing it are specialists and the incentives are clean.

Then the wire clears, and a different problem starts, and almost nobody has planned for that one.

I chair two TIGER 21 Groups in Los Angeles. The Members are founders, CEOs, and wealth creators, and a good share of them arrive either just before or just after the event they spent a decade building toward. What I have watched, consistently, is that the portfolio question gets solved long before the personal one does.

The portfolio question is hard and it is also tractable. There are professionals for it, there is a literature, and there are people in the room who have done it. Preservation, allocation, concentration risk, what to do with a number that is suddenly larger than your experience of managing money. That work gets done.

The question that does not get done is simpler to state and harder to sit with. You built something significant. What now?

It shows up first in the calendar. For twenty years the calendar was set by the business, the business is gone, and what replaces it is not obvious and is rarely as demanding. It shows up next in identity, usually some months in, when the answer to what do you do stops being a sentence you enjoy saying. It shows up in the family, where a conversation that could have been had gradually now has to be had all at once, because the money arrived faster than the shared understanding of what it is for.

And it shows up in philanthropy, which in my experience is where people go looking for the answer and where they most often treat a real allocation decision as a gesture. Giving well is as hard as investing well and gets a fraction of the rigor.

I do not think there is a general answer to any of this. I do think the mistake is treating the closing as a finish line, because a finish line implies the race was the point, and for almost everyone I have sat with, the race was never the point. The people who navigate it best start the second conversation before the first one closes, and they have it somewhere they can be honest.

Health

The constraint nobody budgets for

Most of the people I sit with keep a budget for everything that matters to them: capital, time, attention, the next five years of the business. Almost none of them keep one for energy, and energy is what every other budget draws on.

The quality of a decision late in a long day depends less on the facts in front of someone than on how they slept, whether they ate, and whether they have moved since the morning. That is not a moral point. It is a practical one. Judgment depends on the body, and it gets worse when the body is run down.

I have written about this for twenty-two years, across five editions of The Energy Guidebook. The fifth edition comes down to five things: nutrition, movement, sleep, recovery and connection. The book puts the first three at about 75 percent of the result. Measurement and consistency are about 20. Everything else is the last 5 percent, and that includes supplements, which is the business I am in.

Three things from that work apply directly to people running companies or families.

The first is that the basics are not beneath you. The people I know who are most disciplined about capital are often the least disciplined about sleep, on the theory that they can make it up later. The calendar assumes you can. The body does not. Ordinary things repeated for a decade do more than anything clever done once in a while.

The second is that order matters more than intensity. People who try to fix everything at once rarely fix anything for long. The program in the book runs ninety days, one change at a time, in sequence, because one change that holds is worth more than three that do not.

The third surprised me. I expected connection to fail the test for an essential, because it sounds soft and I wanted a list of things you can measure. The evidence did not cooperate. A meta-analysis of 148 studies and more than 300,000 people found that people with stronger social relationships had about 50 percent higher odds of survival over the study periods. What matters most is frequency. A standing weekly commitment does more than an occasional big evening.

That finding is part of why I think peer rooms matter beyond the decisions made in them. A monthly room of people who know you well is a health habit as much as a business one.

If other people depend on your decisions, your energy is not a private matter. It sets the limit on your judgment, and your judgment is what they are relying on.

Risk

What losing money taught me

The most useful thing I bring into a room is not a win. It is what I learned from a loss that took years to recover from.

Early in my career I built real wealth quickly, in a market that was rewarding almost everyone, and I made the ordinary mistake of reading the market’s behavior as evidence about myself. When the market turned in 2001, most of it went faster than I could respond. Then I spent the next several years rebuilding, developing property across the South Bay, in a business where I carried full responsibility for the outcome and had nobody above me to catch a mistake.

Three things came out of that and I have not been able to unlearn them.

The first is that I can no longer tell the difference between skill and timing in anyone’s results, including my own, until I have seen them through a full cycle. A track record inside a single expansion tells you very little. This makes me a slower and more irritating evaluator of opportunities, and it has been worth it.

The second is about leverage. Leverage is usually discussed as a multiplier on returns. It is more accurately a multiplier on the consequences of being early, and being early is indistinguishable from being wrong while it is happening. I underwrite for the version where I am right and the timing is against me.

The third is the one I use most. Losing money is survivable, and being unable to talk about it honestly is what turns a loss into a much longer problem. The instinct after a reversal is to go quiet, and going quiet is exactly when you stop getting the information that would help. Most of the worthwhile decisions I have made since came out of a conversation I did not particularly want to have.

That is a large part of why I do the work I do now. A room where people are honest about what is not working shortens the recovery.

Public bodies

What a public hearing teaches a board

For six years I sat on the Planning Commission of the City of Manhattan Beach, and for two of them I chaired it. It is not a glamorous appointment. The agenda is variances, appeals, and whether a house on a forty-foot lot can be a few feet taller than the code allows. But I learned more there about how a board should conduct itself than in some rooms with far larger numbers on the table.

The first lesson is that everything is on the record. Every staff report is public. Every vote is public. Every word you say from the dais is transcribed and searchable, and the people it affects are sitting twenty feet away, waiting for their three minutes at the microphone. You cannot manage that with charm. You can only manage it by having done the reading, by asking the question you actually have, and by being able to say, in plain language, why you voted the way you did.

The second lesson is the discipline of the record itself. A commission does not get to decide what it wishes were true. It decides on the findings in front of it, against a code that was written before the applicant walked in. When we turned down the appeals on a contested housing project in 2022, the vote was unpopular with a lot of people I like. It was also the only vote the record supported. I said at the time that we have to work with what we are given. I still think that is most of what governance is.

The third lesson is about the chair. A public hearing runs on time because someone makes it run on time: who speaks, for how long, when the questions stop and the motion starts. The chair’s job is not to have the loudest opinion. It is to make sure every opinion that belongs in the record gets there, and that the body arrives at a decision it can defend. That is the job I do at TIGER 21, and the job I would do on any board.

Private boards do not have residents at the microphone. In my experience they would often be better if they did. The nearest substitute is a board that behaves as though the record were public: reads the material, asks the real question, votes on the findings, and can explain itself afterward in a sentence. Most of the failures I have seen would not survive that test. Most of the good decisions would.

Next

If any of this landed, let’s talk.